Tenant screening compliance is the set of legal rules for how a landlord or property manager gets, uses, and acts on consumer reports during the rental application process.
At the federal level, compliance centers on the Fair Credit Reporting Act. It requires a documented permissible purpose for pulling reports. It requires written authorization from applicants. It also requires a compliant adverse action notice whenever a report influences a denial or less favorable terms.
For a full overview of how fair housing law applies at every stage of the rental relationship, see the fair housing overview guide.
Federal fair housing law adds a parallel rule: screening criteria must be applied consistently and without discriminatory effects. State and local jurisdictions add more rules on top:
- Application fee caps.
- Pre-screening disclosure rules.
- Criminal history timing and lookback limits.
- Protections for applicants using housing subsidies.
Enforcement around screening has stepped up. There have been significant FTC and CFPB settlements against both screening vendors and housing providers. These involved accuracy failures and weak adverse action processes. If your vendor gives you an automated score, see our guide to AI tenant screening, fair housing risks and disclosure rules.
This guide is part of the compliance and legal hub for independent landlords.
Why Screening Compliance Is Now a Documented, Auditable Function
Most landlords know they cannot discriminate in screening. Fewer see that the duty also covers how screening is done. That includes:
- When reports can be pulled.
- What authorizations are required.
- What notices must follow an adverse decision.
- How criminal history policies are set up and documented.
- What disclosure rules apply in the states and cities where they operate.
Take a landlord who uses consistent, written criteria and sends proper notices when denying an application. That landlord has a defensible position when a decision is challenged.
Now take a landlord who uses the same vendor and the same instincts but cannot produce written criteria. That landlord cannot explain why two similar applicants were treated differently and never sent an adverse action notice. This landlord has significant exposure, even if the actual screening decisions were legitimate.
Regulatory enforcement has set clear patterns. FTC action against AppFolio resulted in a multi-million-dollar penalty tied to screening report accuracy issues including outdated eviction records. A later FTC and CFPB settlement with a major screening vendor involved allegations including failure to ensure report accuracy. Landlords who rely on those reports face real downstream risk if they have no controls over accuracy, dispute handling, and adverse action notices.
For a practical breakdown of the 8 most costly screening mistakes and how to avoid them, see the guide to common tenant screening mistakes.
Step-by-Step: Building a Compliant Screening Workflow
Step 1. Map Your Legal Requirements Before Setting Criteria
The fastest path to a screening violation is using one process across all properties without checking the rules in each jurisdiction. FCRA and the Fair Housing Act apply everywhere. State and local rules can change the process a great deal.
New York caps application fees at the lesser of $20 or actual cost. It requires itemized receipts. It also requires that the screening report be given to the applicant within a set timeframe. Washington requires written disclosure of the screening criteria and the name of the screening company before any fee is charged. It also limits the fee to actual cost.
Colorado requires landlords to accept portable tenant screening reports in defined cases, which cuts duplicate fees. California's SB 267 limits the use of credit history for applicants using government rental subsidies. It also requires landlords to consider other proof of ability to pay.
New York City's Fair Chance for Housing law took effect in January 2025. It limits when in the process criminal history can be considered. It also narrows the lookback window after a conditional offer is made. Seattle's Fair Chance Housing ordinance has similar protections with its own local terms.
For a step-by-step guide to reading credit patterns, eviction filings vs judgments, and criminal history under individualized assessment, see the tenant background check guide.
Build a one-page jurisdiction rules sheet for every market where you operate. It should cover:
- The fee cap and any rule to document actual cost.
- Pre-screening disclosure duties.
- Criminal history timing limits.
- Lookback period limits.
- Any protections for subsidy holders.
Treat this as a living document. Update it whenever local law changes.
Step 2. Define and Document Consistent Screening Standards
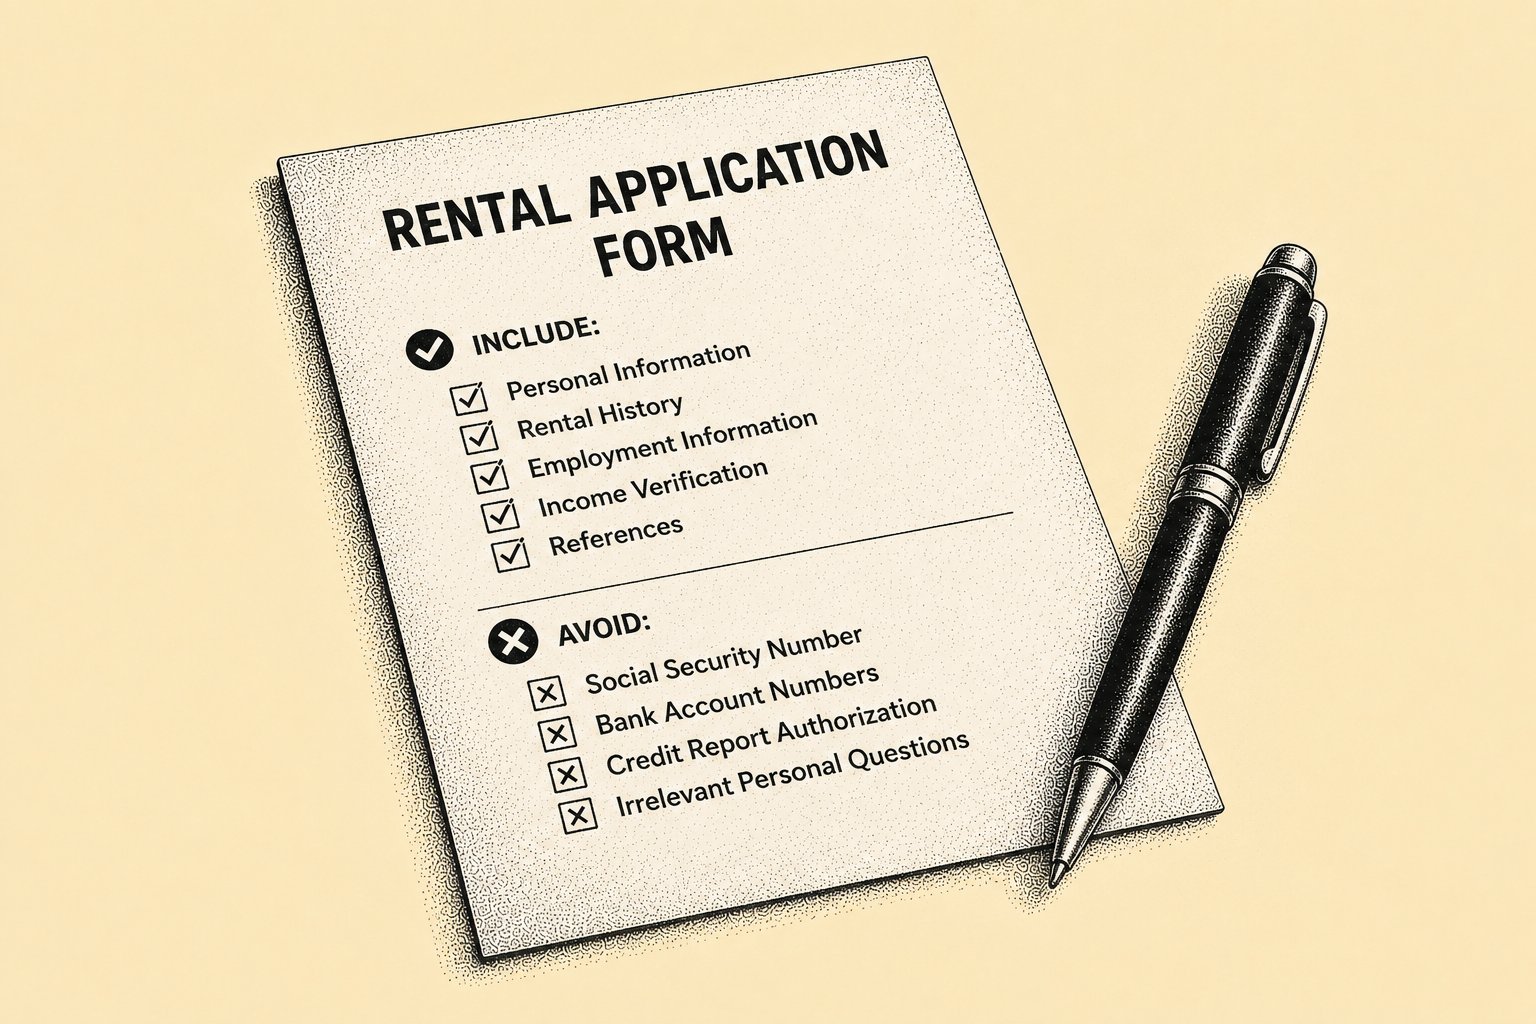
Written screening criteria are the base of a defensible, non-discriminatory process. Criteria should cover:
- How income is verified and the minimum income level.
- Credit evaluation terms.
- Rental history requirements.
- Criminal history policy.
- Occupancy standard.
Tie every criterion to a legitimate business reason. That means the ability to pay rent, the likelihood of following the lease, or the safety of residents and property.
Criminal history criteria need special attention. Blanket bans on applicants with any criminal history can still create fair housing risk because of their disproportionate impact on certain protected classes. HUD rescinded its 2016 guidance on criminal records in November 2025, but the Fair Housing Act still applies, and the FTC notes that a blanket policy of refusing to rent to anyone with a criminal record may violate it. Many states and cities also have their own fair chance rules.
The best-practice approach is individualized assessment. That means looking at the nature and severity of the conviction and how recent it is. It also means asking whether it bears a direct link to housing safety or to the safety of other residents. Arrests without convictions, sealed records, and expunged records should generally be excluded.
A criminal history criteria matrix lists which offense types are relevant and what lookback periods apply. It also lists which mitigating factors are considered, such as proof of rehabilitation or personal references. The matrix should require the same analysis for every applicant with reportable history. The same decision-maker should complete it, using the same form.
For the complete working system for reducing discrimination risk across screening and beyond, see the fair housing compliance guide.
Publish criteria in advance where state law requires it. Even where it is not required, sharing criteria before the application cuts disputes about which standard was used. It also supports the consistency argument that is central to fair housing compliance.
Step 3. Obtain Proper FCRA Authorizations
FCRA compliance starts before the report is ordered. The CFPB has stressed a strict reading of permissible purpose. A consumer report should only be pulled when the landlord has a legally valid reason tied to an actual housing transaction. Pulling a report on a prospect who toured but never applied creates permissible purpose risk.
The authorization for a consumer report must be clear, written, and kept. Many landlords use one application authorization that covers both the general application and the consumer report pull. This is common practice. Even so, the authorization must clearly describe the scope of the consent. It should be kept in the applicant file, tied to the application date.
Your screening product may include an investigative consumer report. That means information gathered through interviews about the applicant's character or reputation. If so, the FCRA adds more disclosure rules with specific timing. Ask your screening vendor whether any part of the product counts as an investigative consumer report. Confirm whether the required disclosures are built into the platform workflow.
Step 4. Send Compliant Adverse Action Notices
The adverse action notice is the most often missed FCRA duty in residential screening. FCRA requires a compliant adverse action notice any time a consumer report influences one of these:
- A denial.
- A conditional approval with less favorable terms, such as a higher deposit.
- Any other adverse change.
The notice must include:
- The name, address, and phone number of the consumer reporting agency that provided the report.
- A statement that the agency did not make the decision and cannot explain why the decision was made.
- Notice of the applicant's right to get a free copy of the report within 60 days.
- Notice of the right to dispute the accuracy or completeness of the report.
- If a credit score was used, specific disclosures about the score.
Send the notice as soon as you make the adverse decision. Log the delivery date, the delivery method, and the report that influenced the decision. Some conditional approvals have conditions driven by the report. Treat those as adverse action and send notice to match. A platform that creates and stores adverse action notices automatically, and ties them to the underlying report, greatly lowers the risk of missed notices.
Step 5. Apply Fee and Disclosure Rules by Jurisdiction
Application fees and disclosure timing are common sources of technical violations for landlords who work in several states. This is precisely because these rules feel like paperwork, not substance.
In New York, a fee above $20 or the actual cost of the screening is a violation. This is true no matter how qualified the applicant is or what the landlord intended. The landlord must also give an itemized receipt and a copy of the screening report within the required timeframe.
In Washington, the screening criteria and the name of the screening company must be disclosed before any fee is charged, not after. In Colorado, an applicant may provide a portable tenant screening report. A landlord who refuses it and charges a new fee may be violating the state's application fairness framework.
Build fee compliance into the front end of your screening workflow. Do not treat it as an afterthought. Confirm the fee cap that applies. Issue a receipt for every application fee. In states that require it, document the actual cost of the screening as the basis for the fee.
Step 6. Retain Records Securely with Access Controls
Screening records are sensitive consumer data. Store them in a central, access-controlled system. Do not leave them in email threads, shared drives, or paper files that pass freely around an office.
The retention file for each applicant should include:
- The completed application.
- The signed consent and authorization.
- The criteria in effect at the time of the decision.
- The screening report.
- The decision record with the specific criteria applied.
- The adverse action notice, if one was sent.
For approved applicants, keep the screening records for the same period as the lease file.
Disputes over screening decisions can come up months after the application was processed. A landlord who cannot quickly produce the criteria, the report, and the adverse action notice is in a poor position to defend the decision. A central system with search, version control, and audit logs helps. It makes it much easier to respond to an inquiry or complaint.
Tenant Screening Compliance Checklist
Pre-screening: Written criteria published or available to applicants before the application. Jurisdiction rules sheet confirms the fee cap, disclosure rules, and criminal history timing rules that apply. Application fee and receipt process matches jurisdiction rules.
Authorization: Completed application received before any report is ordered. Written authorization for consumer report captured and kept. Any investigative consumer report parts identified and required disclosures prepared.
Report ordering: Permissible purpose confirmed: active application tied to a housing transaction. Screening vendor confirmed to keep accuracy controls and a dispute resolution path.
Criteria application: Same income, credit, rental history, and occupancy standards applied to every applicant in the same order. Criminal history reviewed using the individualized assessment form. Blanket bans and arrest-based denials avoided. Exception approval and documentation process followed.
Decision and notice: Decision recorded with the specific criterion applied and the evidence relied on. Adverse action notice sent right away for any report-influenced denial or conditional approval. Notice includes all required FCRA elements. Delivery method and date logged.
Records: Applicant file includes application, authorization, criteria version, report, decision record, and adverse action notice. Stored in a secure, access-controlled system. Retention period applied consistently.
How Shuk Supports Screening Compliance
Shuk integrates with RentPrep for tenant screening, providing credit, criminal background, and eviction history reports. The landlord sets the pass criteria and makes the final decision.
Centralized in-app messaging with email and push notifications keeps applicant communications in one place, not spread across email threads. This helps if a decision is later challenged.
Frequently Asked Questions
What is an adverse action notice and when is it required in tenant screening?
An adverse action notice is a written disclosure required by FCRA. It is required any time a consumer report influences a decision to deny an application or to offer less favorable terms. This includes credit, criminal, or eviction history.
The notice must include the screening agency's contact information and a statement that the agency did not make the decision. It must also state the applicant's right to a free copy of the report and the right to dispute errors. Send it as soon as you make the adverse decision.
Can a landlord use a blanket no-criminal-history policy for tenant screening?
Blanket policies that deny any applicant with any criminal history carry significant fair housing risk because of their disproportionate impact on certain protected classes. HUD rescinded its 2016 guidance on criminal records in November 2025, but the Fair Housing Act still applies, and the FTC notes that a blanket policy of refusing to rent to anyone with a criminal record may violate it.
The best-practice approach is individualized assessment. It looks at the nature, severity, and recency of the conviction and how it relates to housing safety. Arrests without convictions should not be used as a basis for denial.
What state rules most commonly catch landlords off guard in screening?
Some of the most often overlooked rules are:
- New York's $20 application fee cap and report delivery requirement.
- Washington's pre-fee disclosure of screening criteria.
- California's SB 267 limit on credit history use for subsidy holders.
Landlords who expand across state lines often apply one standard from their home market. They do not check whether it breaks the rules of the new jurisdiction. The most practical way to prevent this is a jurisdiction rules sheet, updated whenever you enter a new market.
How should a landlord handle a dispute from an applicant about the accuracy of their screening report?
Send the dispute to the consumer reporting agency that provided the report. FCRA gives applicants the right to dispute the accuracy of information in consumer reports. The duty to investigate and correct wrong information rests with the agency.
Record the date the dispute was received, the referral to the CRA, and any later update to the applicant file. If the report is corrected and the applicant reapplies, review the new report against the same written criteria used for other applicants.
What should be in a written tenant selection criteria document?
A written tenant selection criteria document should cover:
- The income threshold, and how income is calculated and verified.
- The minimum credit criteria, or the credit factors that are reviewed.
- Rental history requirements, including how prior evictions or landlord references are treated.
- Criminal history policy, including the types of convictions considered and the lookback period.
- Occupancy standards.
- The process for reviewing exceptions.
The document should be version-controlled. Keep the version in effect on the date of any decision in the applicant file.